A car loan interest calculator can reveal the difference between a manageable monthly instalment and an expensive long-term commitment. It models how much interest accumulates while principal is repaid. Used carefully, it helps buyers compare offers without visiting several branches. Used carelessly, it can create false confidence because the interest shown on screen may omit fees, changes in rate and the actual amount financed.
Understand what the calculated interest represents
For an ordinary reducing-balance instalment loan, interest is charged on the outstanding debt according to the agreed method. Each payment normally covers interest due for the period and reduces part of the principal. As the balance shrinks, the interest component of a constant EMI generally becomes smaller. This is why a reducing-balance calculation differs from simply multiplying the original loan amount by the annual percentage and number of years.
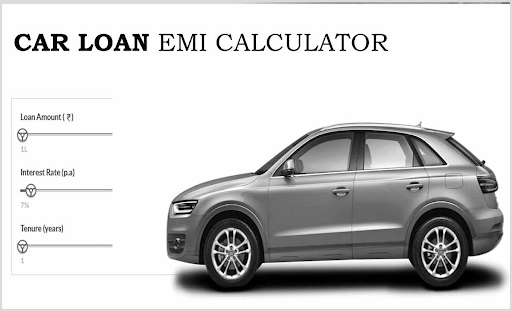
A car loan interest calculator commonly asks for loan amount, annual nominal rate and repayment term. Some tools show just the equated monthly instalment (EMI), while others also display the total interest and full repayment. Always check the assumptions printed alongside the output. The phrase ‘total interest’ usually describes modelled loan interest, not every rupee you will pay to obtain credit.
Build the example around the actual borrowed sum
Imagine a car with a written on-road quotation of Rs. 12 lakh. The buyer contributes Rs. 2 lakh from savings and asks to borrow Rs. 10 lakh. If the lender agrees to fund that full remainder, Rs. 10 lakh becomes the principal for the calculation. This is only an illustrative scenario: some institutions limit which purchase charges they finance.
Using sixty monthly payments and a constant 9% nominal yearly charge on a reducing balance, the estimated EMI is Rs. 20,758. Multiplying the unrounded monthly amount by sixty and deducting Rs. 10 lakh gives approximate modelled interest of Rs. 245,501. The example excludes fees and insurance, assumes equal monthly periods and rounds displayed amounts to the nearest rupee. It does not represent a guaranteed sanction.
Separate three numbers often confused online
For a car loan online, the nominal interest rate is the percentage used to work out interest under the stated method. The annual percentage rate (APR) is a broader annualised measure of relevant borrowing expenses. The total rupee cost is the actual amount of interest and applicable fees paid over the arrangement. These are related, but none is automatically identical to the others.
For applicable retail term loans, RBI disclosure rules call for a Key Facts Statement (KFS) that includes APR and a repayment schedule. A calculator may not be able to reproduce that APR if it lacks the lender’s final fee details and timing of charges. For that reason, use it to explore scenarios and the KFS to examine the written offer.
Do not add a processing fee twice when calculating total outlay. If a charge is deducted from the amount paid to the seller, financed into principal or collected separately at application, its treatment changes both the initial cash requirement and the broader cost comparison. Ask the lender to explain how each fee appears in the schedule and disclosures.
Compare two offers on equal terms
When comparing a car loan online, suppose Lender A quotes a lower nominal rate and larger upfront fee, while Lender B quotes a slightly higher rate with lower disclosed charges. Enter the same borrowing amount and term into a tool for both interest calculations. Then add the correctly identified costs and compare the APRs in their respective documents. A smaller EMI in isolation does not settle which is cheaper.
If one lender allows an early part-payment without an applicable charge and another has stricter conditions, that difference may matter to a buyer expecting a bonus or sale proceeds. Ask how extra payments are applied: some arrangements reduce the remaining tenure, others alter the instalment. An interest calculator that assumes all sixty scheduled payments will occur cannot automatically value an unplanned closure in year three.
Test the danger of a narrow rate assumption
A car loan interest calculator may use a sample rate rather than a personalised quotation. Borrowers with different credit histories, existing liabilities or employment records can be offered different terms. Try the same principal and tenure at several plausible rates, and identify the point where the EMI would become uncomfortable. This creates a useful borrowing boundary even before the final quotation arrives.
Remember that vehicle ownership has a second budget
Before choosing a car loan online, account for vehicle ownership costs beyond interest. Fuel or charging, registration, insurance renewals, routine servicing, tyres and parking continue regardless of the loan schedule. A large down payment might reduce borrowing costs but leave too little cash to cover the next insurance renewal. A longer tenure might improve immediate liquidity while increasing total interest.
Use the result to negotiate clearer terms
Save the car loan interest calculator’s inputs and outputs, then compare them with the sanctioned loan amount and amortisation schedule. Ask about any unexpected difference, including financed fees, altered tenure or another interest method. Choose a repayment plan whose full cost you understand and whose EMI remains manageable during an ordinary expensive month. A good calculator makes the questions sharper; the written loan offer supplies the final answers.